Choosing Properties

Choosing Properties

Mr. ODA has regular emails come in with new listings in the areas we’re interested in. While some of our houses are 2 bedroom, we find it easier to rent 3 bedroom houses. We also are looking to the possibility of resale, which is better for the 3 and 4 bedroom houses.

First, we look at the condition of the property. We’re interested in properties that can be immediately rented, meaning we’re not looking for remodel projects. Most of our properties purchased required no work to prepare it for a renter, and they are typically recently updated. When I say these houses were recently updated, they weren’t top-of-the-line finishes.  Here’s an example of one we purchase 4 years ago, and the pink knobs are still there!

There are a few properties that took slightly more work. We purchased one property that required a whole-house paint job (including trim work) that took a week doing it myself. We also attempted to rent another property with old carpet on the main floor. The potential renter asked if we’d be willing replace it or refinish the floors; we ended up taking a week to refinish the floors, which has paid off in the long run.

Typically, we’re going to replace appliances, paint, and scrub the place down to prepare it for renting. We’re not looking to overhaul the building or do massive capital improvements for that first renter. However, I’ll note that it doesn’t mean we don’t eventually do that. Just this past year, we had several roof replacements/repairs, plumbing replacements, and HVAC repairs.

We want the house to be in good condition to keep a renter there (we’ve actually had very low turnover), make it easy to re-rent it when there is a vacancy, and to make it attractive for any future sale. We’ve noticed that homes that were typically owned instead of rented are in better condition than if it was managed by a landlord. We seem to struggle wanting to move forward with houses that are currently rented because of all the deferred maintenance.

We have been under contract on multiple houses that we walked away from after the home inspection (e.g., knob-and-tube wiring, vertical clearance requirements on stairs, remnants of a previous fire found, poor patch work). Don’t feel like you’re in too deep if the inspection comes back to show a lot of improvements are necessary. It’s a hard mentality to talk yourself (and your partner) through because you’ve spent time looking at the house, reviewing rental comps, possibly reviewing current lease agreements, and spent the money and time for the home inspection. But keep in mind that it’s not worth purchasing the house and spending more than you’d like to keep the house standing and rentable.

Then, in broad strokes, we’re watching the 1% Rule. This means the monthly rent should be 1% of the purchase price (e.g., a purchase of $100,000 house should yield $1,000 per month in rent). Review current rent prices in the immediate vicinity. We’ve purchased houses in areas that have several rental properties, so it’s been fairly easy to identify a rate based on the number of bedrooms and bathrooms, as well as the amenities we can offer (e.g., appliances, lease term, parking availability). In future posts, I’ll provide the details of each of our purchases.  

Here’s a break-down of our current properties related to the 1% Rule. 

You can see that we didn’t hit the 1% on 5 of them. The first had a tenant when we purchased it 4 years ago; we’ve risen the rent once and plan to raise it to $1200 at the renewal term in July (so raised the rent $50 every two years). The bottom two were in a market that we were unfamiliar with, and even though we thought we would yield $990 easily for rent (yes, is still below 1%), the houses were in excellent condition, so we looked to the future value in the decision making. Unfortunately, we didn’t close on these until September, which is difficult to find renters. We didn’t have many showings at ~$1,000 rent. We ended up lowering the rental price by offering an 18-month lease so that the future rental timeframe was in the spring, and we offered the rest of October as free.

Mr. ODA developed a spreadsheet to calculate all the costs associated with owning the house, which helps determine whether the house fits our portfolio goals, especially if it doesn’t exactly meet the 1% Rule. This spreadsheet makes assumptions for routine maintenance costs, capital improvement costs, vacancy assumptions, insurance, mortgage interest, etc. Calculate the monthly rent less than the monthly cost of each of these assumptions to arrive at the monthly cash flow. Annualize the monthly cash flow, and then divide it by the down payment and closing costs to arrive at a ‘cash-on-cash’ return, which we’re looking to be at least 8-10%.

Next, we examine the neighborhood. We have thresholds for prospective tenants, which typically yields to a middle-of-the-road neighborhood. We’re not looking for a perfect, upscale neighborhood to own a rental because these types of homes rarely meet the 1% Rule. I utilize Trulia to examine the crime rates of the area. We want to offer homes that are in reasonable city locations.

I had fully vetted one house and determined it was worth our purchase. A similar house, with an upgraded kitchen, was for sale a couple of blocks away. I assumed it was the same neighborhood and didn’t do my due diligence. The house showed very well online, and we had several showings from qualified individuals, but then they’d check the house details, only to find out that it was in a high crime zone. We ended up having to lower our credit score threshold to find a renter (compensating with additional security deposit), then had difficulties for over a year collecting her rent, which really should have been expected. We have since sold off that property. 

If all these steps, including the cash-on-cash evaluation, should take about an hour. If we get this far, we go see the house. If the house is in the condition we expect it to be based on the pictures, we make an offer. Our Realtor will write up that offer the same day. Recently, many houses have been in a multiple-offer scenario. This is another trap to not get sucked into. After so much time vetting the house, it’s easy to be attached, especially if you find very favorable data (e.g., you can get rent higher than 1%). It’s not worth owning the house if you have to purchase it at a higher price than you’re comfortable at; it must be a business decision, purely based on the financials.

Keep an eye on listings daily or weekly to keep a pulse on the neighborhoods you’re interested in, evaluate the property condition, consider the 1% Rule and evaluate the detailed financial cash flow, don’t skip the home inspection nor should you ignore the results of it, and keep it a business (not emotional) decision.

Mrs. ODA Taking Over

Back in 2018, my husband started this blog and introduced himself. I had a different upbringing than him, and he asked me to introduce myself back then, but I didn’t make the time for it (something about being a first-time mom and going back to work 🙂 ). Now I’m ready to take over the majority of this task, but first wanted to share more about me. You can see whether it’s my post or his by the author listed by the post title.

I’ll come right out with it: I didn’t grow up with an allowance. I don’t have a pretty, neat story like he does. I mostly learned about the value of money through hardships in college, and then I let Rob lead my finances before we even started dating. That’s the quick version; now the long.

I had a check register, and my mom taught me how to balance a checkbook. I found the process fascinating and kept up with it, but it was always in terms of play, not actual budgeting of my money. Quick sidetrack: I remember having a sleepover at a friend’s house with 3 or 4 other girls. I was so excited about my new checkbook and how to manage the register, but we went overboard and I regretted how many checks we used in my checkbook. I hid at the top of the stairs to the basement, sulking in my decision and making it awkward for everyone. Things you wish you didn’t remember, but they always seem to surface and renew that 12-year-old’s embarrassment. 

I had chores, but they were expected to be accomplished without payment. Before you feel bad for me, it wasn’t what it seems. My parents were GOOD to us. If I went to the movies with my friend, my dad handed me cash. I used to hang out at the mall regularly. I rarely bought anything other than McDonald’s and candy, but I can honestly say that I don’t know how I made the money to even buy those things (I’m assuming it was related to birthday cards). 

I didn’t have a job until after high school. I really don’t know why; it wasn’t discussed and my friends didn’t work, so it wasn’t a thing I thought about. The first I remember it being discussed was right before graduation. I walked through my town’s main street and asked each business if they were hiring. That’s how I ended up working in a bagel shop every morning at 5:30 am. I was paid ‘under the table’ and continued to not understand the value of money and how taxes affect my pay. 

During the summer after my freshman year of college, my dad told me that I needed to have a job before I could have a car. I was already back at the bagel store in the early mornings, but it wasn’t ‘full-time.’ I applied to several places, but not many places got back to me. I eventually got a second job working at a catering hall in my town, which took up my Friday nights, Saturday days and nights, and Sunday afternoons. For some reason that I can’t remember, this wasn’t enough to meet “full time job” level of income or hours worked because I then started working at K-mart as a cashier. I worked 3 jobs that summer. At the end of the summer, my dad let me bring his car to school (3.5 hours away). I was disappointed that I thought I’d be getting a new(er) car (disclosure: I expected to pay for it, but I thought the goal here was to prove I could make enough money to support the payment of it, and he’d help me get the car).

I was driving home for winter break, and the car just stopped accelerating up a hill on the interstate. Turns out, second gear on the transmission was shot. My dad said I could pay to replace the transmission and the car would be mine. I didn’t like the idea of having an unreliable car 3.5 hours from my family and was still salty about all the hours of work I had put in over the summer. I decided I wanted a leased vehicle because it didn’t require a down payment (amazing logic…), and I ended up with a Honda Civic for about $350 per month. At the time, I was working at JCPenney for about $5.85 per hour while attending school. 

During the school year, my parents told me that they wouldn’t pay for me to live on campus in my junior year. They said either I needed to take a loan out or become a Resident Advisor (RA). Being an RA seemed to interfere with my social life, so I decided to move off campus because then I could pay month-to-month with the money I earned instead of needing a loan to pay a semester’s worth of housing up front. However, it wasn’t easy. All my friends were still living on campus, and I didn’t want a random roommate. I lived on the first floor of a house where my landlord lived upstairs. I couldn’t afford it, but I was determined to make it work, meaning I didn’t turn the heat on. I had blankets though … in Albany, NY. My mom didn’t appreciate finding out that I hadn’t turned the heat on by Halloween, and she started sending me some money. She sent me $100 for 6 months in a row, and that covered my utility bills through the winter. 

When I started working, my parents taught me to contribute to my TSP (401k). I put the amount required for full match (5%) because if I didn’t, that would be like throwing away free money. Then they taught me that each time I got a raise, increase my TSP contribution with that difference since I was already living comfortably without it. I followed all of that advice and continue to share that insight with others.

Enter Mr. ODA. He showed up at my office nearly 2 years after I started working there. One night, before we were dating, he asked me my social security number. Odd! He told me I needed to build credit and was signing me up for a credit card that I was to pay off monthly. Multiple people had told me that I should always carry a balance on a credit card to “build credit,” and he was quick to right that wrong. Shortly after we started dating, he had me max out my TSP contributions and start a Roth IRA, and the rest is history. He’s lucky I’m such a quick learner. 🙂

401k/TSP Loans

Working for the Federal government, our 401k is called the Thrift Savings Plan (TSP). We max out our contributions each year. As a means of bridging down payment gaps, we utilized a little-known option – the TSP loan.

Per TSP.gov, “When you take a loan, you borrow from your contributions to your TSP account. Your loan amount can’t exceed the amount of your own contributions and earnings from those contributions. Also, you cannot borrow from contributions or earnings you get from your agency or service.” There are two loan options: general purpose and real estate. There are different requirements to meet for each type of loan.

First, here are some items to consider in the decision-making. While these rules pertain specifically to the 401k program provided to Federal employees, TSP, your employer’s 401k service provider should have a similar program for taking a loan from your account and rules associated with paying that loan back.

  • You have to begin making loan payments immediately after your draw down. A general purpose loan must be repaid within 5 years, and a primary residence real estate loan must be repaid within 30 years but you have control over the amount of each payment, as long as the amortization keeps the repayment within the required period. 
  • You pay interest on the loan, which is set at the ‘G Fund’ rate. According to the TSP website, the interest rate is 0.875% as of 1/17/2021. This interest payment is paid into your TSP account.
  • There is a loan fee of $50. 
  • You must be currently employed by the government to take the loan, since repayment is processed through payroll deductions, and if separating from the government you must repay the loan in full within 60 days of separation.

The common talking point working against using a 401k loan is that you need to weigh the loss of compound growth on the balance of your TSP against what the loan will gain you. Many financial talking heads will warn you of using your retirement account for immediate, frivolous purchases. But, used appropriately and strategically, Mr. and Mrs. ODA fully believe that 401k loans can open up financial doors much earlier than through more “traditional” means. 

Our first loan was for our primary residence. While Mr. ODA was an excellent saver through college, he expected to buy a house for about half the cost of what a very basic house goes for in Northern Virginia. Our opportunity cost was private mortgage insurance (PMI); did we want to pay PMI (an added cost that a bank adds to your monthly loan payment to mitigate the risk if you don’t bring a 20% down payment to the house purchase) or take out TSP loans to make up the difference for our down payment? Taking out a loan was ‘out of the box’ and seemed controversial. However, paying PMI indefinitely and being subject to the bank’s decision on when PMI could be removed was more concerning. PMI is building the bank’s “pockets,” while the interest on a TSP loan is going back to your TSP account. 

We decided to each take a residential loan from our accounts. I took a $15,000 loan and Mr. ODA took a $25,000 loan. By taking a TSP loan, we were losing out on the earnings of the accrued balance, but the repayment to ourselves of the G-fund rate was a reasonable trade off. Plus, we could put any extra money towards the loan at any time, thereby increasing our TSP balances faster. 

My loan draw was 7/2/2012, and I had it paid off by 3/17/2015. We could have stretched the payment over the full 30 years to fully leverage our money, but at the time, owning rental properties wasn’t on our immediate radar. However, two incentives to pay a TSP loan off faster than a allowed amortization are 1) that you can only have one loan of each kind at a time, and 2) you can’t request a new loan within 60 days after you paid off a TSP loan. Then there’s that opportunity cost; we wanted to get our money back into our tax incentivized account as quickly as possible to get it working for us again. 

Since our experience was positive for these two loans, we kept this option on the table for future transactions. In 2016 and 2017, we purchased 9 rental properties using regular savings from our high savings rate lifestyle and the equity we were able to cash in from the sale of our first primary home. To cover the down payment of the last few purchases, Mr. ODA and I each took a general purpose loan of $50,000, which is the maximum amount for such type of loan. The loan rate at that time was 2.25%, which was a great lending rate back in 2017. We paid my loan off first, fairly aggressively using the cash flow from the rental properties we purchased, knowing that since I would be separating from the government once we had kids it had to be paid sooner than later. Mr. ODA has adjusted the repayment amount per pay check several times since 2017 to meet our cash flow needs. The loan was issued on 9/1/2017 and currently has a balance of $12,370. 

When looking at the opportunity cost comparison for the rental property purchases, we determined that the 4 ways we make money in real estate investing outweighed the likely (and what actually turned out to be very lucrative) gains of the stock market.

  1. Cash Flow – Profit from rent after all expenses are paid.
  2. Principal Pay Down – The amount the tenant essentially pays out of your mortgage payment that goes directly to the equity of the house.
  3. Appreciation – The increasing of property value based on the market.
  4. Tax Advantages – Being able to utilize the tax code in an advantageous fashion as a business owner. 

By carefully evaluating each property to ensure we had near-guarantees of all 4 of these methods working, we thought that the benefits of owning more rentals outweighed the loss of share ownership in our TSP accounts. 

January Financial Update

There are a lot of updates to share over the next few weeks to fully explain how our net worth changed so drastically in two years. For the time being, here’s a snapshot of this month’s status.

*The original post had IRA at $313,630, but that was double counting an investment account between ‘IRA’ and ‘taxable’ categories. The image above was updated as part of the February financial update to reflect the accurate January IRA total.

As a quick summary from where we left off, Mrs. ODA’s 401k loan and that 0% interest credit card were paid off. However, we have a new 0% credit card that now has a $5,000 balance that will be paid off in the next month. One of the investment properties was refinanced, which included a cash out option, increasing the mortgage balance. We purchased two new properties in September 2019.

These updates will occur around the 15th of every month. The investment properties’ mortgages are paid on the 10th of each month, so the majority of changes in our finances occur at this time. Future updates will include spending categories as well.

New Year

In honor of my last post being two years ago, we’re starting this back up! Here’s a summary of what’s been happening, and I’ll delve deeper into specific topics with future posts.

In January 2019, Mrs. ODS was back at work part time after having our first child, burning through sick leave, getting ready to quit her job. In February 2019, the Federal government was shut down for several weeks, and I found other tasks to occupy my time, including being the full-time caregiver to our son. I took a temporary assignment over the summer of 2019, moving my family to Lexington, KY for 3 months. My wife was pregnant with baby #2, which wasn’t easy. On January 2, 2020, she was admitted to the hospital for pre-term labor at 26 weeks. Luckily, they were able to stop contractions and send her home for bedrest for the next 10 weeks. A week after the country shut down, baby girl was born full term and healthy. Living through a pandemic and limiting our social circle while at home with a newborn and toddler (19 months apart) made us realize how we wanted to be closer to family. On a whim, we agreed to move to KY. Everything played out a lot faster than we expected, and we sold our VA house in September 2020, moved into our new home in KY in November 2020, unpacked, celebrated the holidays, and here we are. We both feel better suited to continue to build these efforts started so long ago.

Here are the goals: teaching posts, story (background) posts, and monthly financial updates. Each post will be categorized into one of these for ease of future searches. We’ve made a lot of financial decisions over the past two years and have a lot to share!

TAXES! Part 2 – Is Your Bonus at Work “Really” taxed more?

Hopefully you read my previous post trying to dispel some incorrect understandings of how marginal tax brackets work. This will build off of that, including showing how the marginal tax brackets for annual income affect the “per paycheck” payroll withholdings your employer processes before paying you.

Let’s take another common misconception, the payroll tax withholding.

When you start a new job, your employer likely hands you a W-4 to fill out. This tells them how you want your federal taxes to be withheld from your paycheck. This depends on your filing status, the number of dependents you have, the way some of your personal activities throughout the year may affect any tax credits or deductions you’ll claim, etc. The W-4 is used to approximate your federal tax liability for the year, divided by the number of paychecks you’ll get in the year.

download

I’m going to look in my crystal ball and know that my federal tax liability for 2019 will be $13,000. I want to fill out my W-4 so that my employer knows to take out $500 of my paycheck every two weeks to pay the tax man on my behalf.

This is easier said than done, and most employers will allow an employee to adjust their withholdings throughout the year (I can do it for every paycheck if I needed or wanted to).

When you file your taxes in the winter/spring of the following year, this process analyzes your tax liability (what you owe based on deductions, credits, income, etc) and compares it to how much your employer paid on your behalf throughout the year. If your employer withheld too much, you get a refund. If your employer didn’t withhold enough, you have to pay. There are differing opinions on how to strategize this situation, but a general rule of thumb should be to match as well as possible your withholdings to your projected liability.

  • If you get a refund, you’ve given Uncle Sam an interest free loan on your money for several months or the whole year. However, this can be a forced saving tool that people use who are scared they’d spend that money if they received it in their paycheck. Others see this as a cash windfall they receive in the spring and use it to splurge on a big purchase.
  • If you owe money, sometimes there are fines for owing too much, and it can hurt to have to shell out a big sum of money at the beginning of every year, if you weren’t saving for it and didn’t expect it.

Where things get tricky, and people start to misunderstand, is if people get a bonus at work, or work some overtime, and get a higher paycheck than normal.

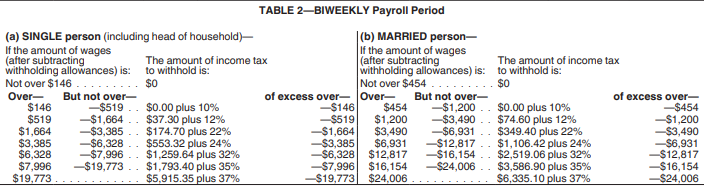
Payroll processors use a chart similar to the tax brackets, where they know your filing status and the number of exemptions you requested on your W-4, and use your income for that pay period to determine how much federal tax to withhold.

If every paycheck you get in the year is for working the same amount with the same salary, your withholding amount will not change and your taxes will be easy to follow and understand.

When it changes, payroll processors do not look at your yearly salary or previous pay periods. They only look at the dollar amount that you earned for that paycheck.

Let’s say you earn $2,000 per bi-weekly pay period in 2019. You file single with 1 exemption. Each exemption (withholding allowance) is worth a deduction of $161.50, so you can deduct $161.50 from your taxable wages for every paycheck for the purposes of reading the payroll withholding charts. (This dollar amount comes from the IRS, as part of their math for how withholdings are estimated to determine tax liability.) Now, you can say you “earned” $1,838.50.

More information on this can be found here, on pages 22 and 44 specifically.

capture

From the chart, you owe (will have withheld) $174.70 plus 22% of the amount over $1,664, which is a balance of $174.50. Times this amount by 22% = $38 (rounded). This totals $213 deducted from your paycheck.

Let’s say that happens 24 out of the 26 paycheck you get this year, but in one, you get a $2,000 bonus, and in another you work $500 worth of overtime extra.

For the check with a bonus, your payroll processor knows you earned $4,000 that pay period, independent of what has happened the rest of the year. Using the same table, your tax withholding will be $553.32 plus 24% of what you earned above $3,385 (don’t forget to subtract your exemptions). That’s $109 more dollars. So you’ll have $662 deducted. That’s a big difference from your $178! Makes the bonus come with a tad bit of bad news, right?

The overtime paycheck works similarly, but because it’s only a little bit more money that paycheck relative to the norm, your tax withholding that check is $323.

Let’s add up your whole year.

24 paychecks of $2,000 income = $48,000 with ($213 times 24) $5,112 taxes withheld

One paycheck of $4,000 with $662 withheld.

One paycheck of $2,500 with $323 withheld.

$54,500 in earnings and $6,097 withheld.

Federal Income tax liability is 10% of $9,700, then 12% from $9,701 to $39,475, then 22% for the rest; this comes to $7,848. However, our system includes a standard deduction of $12,000. This means that you can take $12,000 off the top of your earnings and it won’t be taxed. We’re going to calculate as if you earned $42,500 for the year.

Your tax liability for the year is $5,208. With $6,097 withheld by your employer, this means you should expect an $889 refund!

A couple things were in play here. You claimed one exemption. You could’ve easily claimed a second exemption for some or all of the year to have less deducted from each paycheck to more closely match your eventual full year liability.

Secondly, those two paychecks where the payroll processor charged you extra tax, your paycheck was proportionally smaller, which means your refund at the end of the year was higher. You weren’t ACTUALLY taxed more for that bonus check, you simply had more withheld, a majority of which you’ll get back when you file in the winter/spring of the following year. The bonus check had an even more profound difference because the marginal bracket it fell into that period was the 24% bracket!

If your employer allows as many withholding/exemptions adjustments as you want, you can track your tax withholdings and projected liability changes throughout the year to strategize and minimize your potential difference between the two numbers.

In summary, your total annual income is the only thing that affects the tax liability when you file income taxes at the beginning of the following year. It does not matter if your paychecks were consistent, all over the place, front loaded, back loaded, or any other weird scenario that might happen with bonuses, overtime, raises, job changes, etc. Those variables do affect a single particular paycheck and how much cash you bring home in net that week, but the effects of that can be mitigated by shifting withholding amounts with your payroll processor and planning ahead by tracking your numbers.

images

Reminder, do not confuse payroll tax withholdings from your tax liability. Withholdings are an estimate, meant to match your projected liability. Filing your income tax at the end of the year simply remediates the difference between the two total amounts. If you had too much withheld, you get a refund. If you didn’t have enough withheld, you’ll owe the tax man.

HAPPY TAX SEASON!

TAXES! Part 1 – What are Marginal Tax Brackets?

Recent national media, Facebook, and personal interactions served as the catalyst for these posts on taxes. There is a lot of misinformation and misunderstanding of the way things work, which create opinions and divisiveness not necessarily based on fact.

First, let’s talk about tax brackets and the key word for the American tax system: marginal tax brackets.

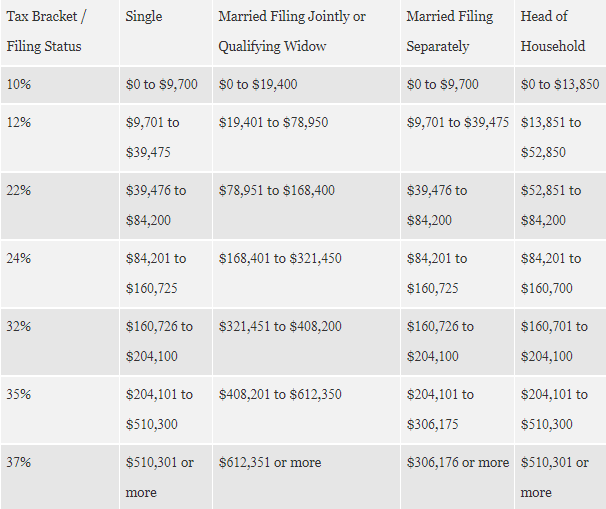
In 2019 there are 7 tax brackets: 10%, 12%, 22%, 24%, 32%, 35%, and 37%. Each of these brackets has varying dollar thresholds for the 4 filing statuses: single, married filing separately, married filing jointly, and head of household. Once you establish under what status you are filing, you know where each dollar you earn will fall in the brackets on the chart.

capture

What I’ve heard many times before, and still see implications of misunderstanding in the media, are folks that think that the last, or highest, dollar you earn is what dictates what tax bracket you fall in. This is incorrect.

In 2019, single filers get taxed on 10% of their income up to $9,700. That means that the first dollars they earn are taxed at 10%, but the $9,701st dollar they earn is taxed in the next bracket, or 12%. The 12% bracket goes to $39,475. Similarly, the $39,476th dollar they earn will be taxed at 22%, and so on.

Individuals that say they do not want that raise, or to make more money, because it would put them in a higher tax bracket are sorely mistaken. Yes, the higher dollars they earn would be taxed more, but those dollars do not suddenly make all the lower amount of dollars be taxed at the high rate too. Those lower amounts stay in the marginal brackets they already were being placed in, based on the way the charts work.

Another single filer example (simplified for easier illustration). You make $80,000, which is the 22% bracket. Taxes for the year are figured as follows.

10% for $9,700 = $970

12% for $9,701 to $39,475 = $3,573

22% for $39,476 to $80,000 = $8,915

For a total tax liability of $970 + $3,573 + $8,915 = $13,458

If you make $80,000 and have to pay $13,458 in taxes, that is 16.8% of your income, not the 22% that the “tax bracket you fall in” might create the perception of.

Say you get a $10,000 raise to $90,000.

We know an $80,000 salary pays $13,458. Let’s add the taxes for the final $10,000.

$4,200 of that is still in the 22% tax brackets, so we can multiply = $924

$90,000 minus $84,200 = $5,800 in the 24% bracket = $1,392

So total taxes are $13,458 + $924 + $1,392 = $15,774.

That represents 17.5% of your income of $90,000 being paid to taxes, not the whole 24% bracket.

If we did not have marginal tax brackets and that raise really did bump all of your dollars up, or if it was calculated in a manner that many Americans think it is, then $90,000 times 24% = $21,600. It would look like your $10,000 raise caused you to pay $8,142 more taxes.

Good thing it doesn’t work that way!

Tax Loss Harvesting

We’re in a market downturn. These are expected, happen fairly frequently, and contain strategies to efficiently optimize the times they happen. One of those strategies is tax loss harvesting.

This year, we “benefit” even more from this strategy because the downturn is happening at the end of the year, at a time when savvy personal finance folks are thinking about all the varying ways they can reduce their tax liability for the closing year.

For the last decade, we’ve been in an uncommonly long and strong bull market, so many young people have no experience adapting to a struggling market and understanding ways to harness the red numbers.

Tax loss harvesting involves selling shares of a “losing” stock, fund, bond, etc and immediately purchasing a similar asset that’s “on sale” to maintain exposure to the market, hopefully buy at the low point, and prepare yourself for the eventual market upturn.

You cannot sell and buy the same stock or fund in this process because that would invoke the “wash sale” rule that disallows claiming capital losses. If you re-buy after thirty days, it’s no longer considered a wash sale.

The reason for utilizing this strategy is to be able to write off capital losses on taxes come April. This could offset earned income, other capital gains, dividends, passive income streams, etc. Paying fewer taxes is the goal, always, right?!

It could even have the double benefit of allowing you to get rid of a stock that doesn’t have a bright future in exchange for one that you think might be better.

Minor issue

One caveat to this strategy: you’ve now placed yourself in a lower dollar value cost basis in the new security you’ve purchased. When you choose to sell that, you’ll be subject to higher capital gains amounts. There are strategies to minimize that too. Tax gains harvesting is something people frequently employ. You do this in a year where your taxable income is lower (preferably below the $77,400 married filing jointly threshold for 2018) so that you can pay less or zero in capital gains taxes.

tax planning

My circumstances

Personally, with Mrs. One Dollar Allowance quitting her job in 2019 to focus on child rearing and managing our rental properties, this year should be the highest tax liability we have in quite some time. Harvesting our losses this week will have a more substantial effect than it would in future down years, and will make the availability for tax gain harvesting in future up years more “profitable.”

Good luck to everyone in this tumultuous holiday week. Shutdowns and market losses don’t lend to great things on the news, but at least this strategy can add a silver lining to your end of the year tax decisions.

October Financial Update

Tracking your net worth allows for a full picture of your finances. It gives a complete understanding of assets across all classes, as well as liabilities or expenses that you are indebted to. Without knowing what this picture looks like, it wouldn’t be possible to accurately strategize financial moves or create short and long term goals.

This post will describe my family’s assets and liabilities, the changes that have occurred in the last month, and why.

Assets

Cash Accounts

End of September: $9,489
End of October: $5,401

Changes: Paychecks; rental income; paying mortgages, credit cards, utilities; accelerating debt payoff; investing

401k (Index funds)

End of September: $493,441
End of October: $473,748

Changes: employer contribution, paycheck contribution, and personal loan payback totaling $13,880; market fluctuation

IRAs (Index funds and Mutual funds)

End of September: $159,622
End of October: $151,148

Changes: $965 contribution; market fluctuation

Taxable investments (Mutual funds and individual stocks)

End of September: $102,435
End of October: $98,800

Changes: $96 dividends; market fluctuation

Personal Residence

End of September: $389,089
End of October: $389,804

Real Estate Investment Properties

End of September: $1,068,957
End of October: $1,074,345

Changes: 10 investment properties’ market value fluctuations

Note: 2 vehicles owned outright

Liabilities

Real Estate Investment Mortgages

End of September: $628,379
End of October: $626,739

Changes: mortgage paydown

Personal Residence Mortgage

End of September: $269,495
End of October: $268,844

Credit Cards

End of September: $9,706
End of October: $9,236

Changes: $1,100 payment on 0% card balance; $861 payments on all other credit card statements.

Spending:

  • Grocery – $342
  • Restaurants -$174
  • Online Purchases – $75
  • Clothing – $76
  • Gas – $99
  • Travel – $234
  • Business expenses – $375
  • Cable/Internet – $55
  • Miscellaneous – $122

Summary

The stock market was not kind to us this month, but that just means we bought more shares on sale when we made our contributions! Our goal over the next few months is to pay off the rest of our 0% credit card and the remaining obligation of Mrs. ODA’s 401k loan.

unnamed

The Son’s Perspective on a Few Parenting Strategies to Ensure Financial Success Later in Life

Student Loans

One of the things I have not had to be saddled with in my young adult life is student loan repayments for my wife or me. We both went to state schools, not the fancy private schools that really don’t typically provide much better (statistically) of an education anyway. My wife’s parents paid her tuition all 4 years, and her housing the first 2 years. She got a job to pay her housing otherwise.

Student_Loans

I’ve had a lust for learning for as long as I can remember. I taught myself geometry at home while I was learning algebra at school so that I could compete better on the math team in middle school. I began taking accelerated classes in 3rd grade, went to the “gifted” middle school program, was one of 30 kids in my county of 3000 freshmen to be accepted into the math and science program in high school, and went on to get a full academic scholarship to college. It covered tuition, housing, food, books, and a small stipend. I also applied for a couple small ad hoc scholarships that gave me some extra spending money those 4 years.

Side note – I finished 16th in my class and opted to go to a state school with financial aid rather than a private or more prestigious school that I would have to pay for. My parents said 2 things early on: If you get a scholarship to college they’d buy me a car (hey, cheaper for them) and if I didn’t get a scholarship, I’d be going to the local state school. Massive student loans and private/out of state tuition weren’t an option. I am so indebted to my parents for many of the hard lines they drew, knowing what was best for their children despite us not being able to see it at the time.

Anyway, each step of my academic career prepared me for the next. I worked hard in elementary school to test into the middle school program. I really developed my passion for math in middle school and used it to get into the high school program. My success and test scores in high school propelled me to a college scholarship. My work ethic in college, despite the many factors that some adolescents fall victim to, had me graduate with honors and find an engineering job with the federal government – in the midst of the recession when the vast majority of all my graduating classmates couldn’t find work.

I was lucky to be born with a propensity to learn quickly and retain information that allowed me to succeed in school. However, I did not squander that gift and worked hard to use it efficiently and make smart decisions with my future in mind.

scholarship

My parents instilled values in me that complemented my internal motivation to succeed. They created expectations that told me that anything less than success wouldn’t be tolerated. They even “dangled the carrot” of the new car that really catalyzed my drive (pun intended) to get that scholarship. These actions, both direct and indirect, in our household throughout childhood built the foundation for a solid academic career that got my finances and my net worth started in the positive direction once I became an adult.

Personal Finances

One of my earlier posts  focused on the ways my parents set my values for frugality, strategic decision making and spending, and saving. When I got money as a kid, I first saved it, then chose to carefully spend it when something was worth buying. When I got money from grandma for birthdays and Christmas, I put that money away for a rainy day rather than going and spending it all the next day. My wife and I still operate that way. Rather than looking at this “extra income” as a source of money to go buy something we don’t need, we simply add that money to our regular financial accounts to fund our next goal or debt payoff.

My parents led by example. When we traveled, we stayed at lower cost hotel chains, or with family and friends. We drove all of our vacations because flying was expensive. We brought our food and ate meals outside of restaurants where possible. Our day to day didn’t involve many restaurants. Feeding a family of 5 adds up quickly when you eat out. We didn’t have video games, a big screen TV, or the highest cable package, as socializing and playing outside is far more important to adolescent development than sitting behind a screen like many kids of the current generation.

frugal

As soon as I was old enough to understand, my dad began teaching me about investing. While in high school he helped me buy my first mutual fund (one that I still have, but I’m trying to find the right time to sell now that I realize the horror of high expense ratio funds!). When I went to college, I learned that he had been investing on behalf of my siblings and me for many years, and then gave us the money he’d invested as a gift to get us started in the real world.

Everything I saw, and continue to see, my parents do with any relation to finances or income and expenses is deliberate, and with the future in mind. This has translated to my own daily thinking. It became a habit, became natural. Since these thoughts and weighing of fiscal pros and cons have been part of me for as long as I can remember, it’s easy for me to analyze options on the fly and choose the best decision for my family in the moment. I don’t even have to try.

The one place that I would say I have deviated from my parents is my willingness to turn off the conservative thought process and attack my financial future with more risk and aggressiveness. However, growing up in a household of conservative money management gives me the past experience to draw from that keeps me grounded as I leverage more debt and make choices to expand my net worth as quickly as possible.

Stay tuned for more on the net worth conversation…