House1: Turnover – Original Tenant

I don’t usually spend much time on the tenant themselves, but there are a lot of lessons to share with this one.

We had to turn this house over last year when the two ladies who lived there moved to Georgia. They had been there a couple of years. We were busy when their lease ended, so when they asked for another month, I had agreed. But then we were on an awkward schedule for leasing. Our candidate pool was pretty low. We ended up settling on this lady who said she needed to find a place fast because her landlord was selling the property she was living in. She had told us that she needed to wait for him to return her security deposit to get us our security deposit. She told us this after we had already started the process of getting her into the house, so we just had to accept it. It took her 3 payments to get us the security deposit. That was the first red flag. She continued to be an issue for her entire tenure.

She was the type of person who wanted to hide behind her faith while continuing to treat us terribly. I can’t standing living through something like that.

The second red flag came when she kept saying her mail key wouldn’t work. She would take a week to respond to Mr. ODA with information on how it didn’t work. Finally, after several weeks of back and forth, Mr. ODA drove over there. He put the key in the mailbox number he told her and it worked fine. This doesn’t seem like a big deal, but coupled with everything else we went through, it was telling.

LATE RENT

The third red flag was everything about rent. In February, she paid $1000 on the 5th. Since she paid the majority of rent up front, we didn’t charge her a late fee. She paid $350 on the 15th. Not bad. She paid when she said she would. Then it just keeps getting worse.

She let us know that she was going to be late for March. There wasn’t great communication, but we received half of rent on the 7th. After much follow up, she paid the second half of rent and $50 towards the late fee on the 28th. When people pay that late in the month, I know it’s going to cause the next month to be late. So April comes along and she barely tells us what’s happening. She just keeps saying she needs more time and eventually pays on the 25th with $50 of a late fee. No partial payments. Mr. ODA expresses the need for partial payments and to communicate what is going on. She acted like we were out of line for expecting rent. Then comes May. More bad communication. Mr. ODA finally expresses that the late fee is actually $135 and that’s written in the lease agreement (she’s surprised by that). We get rent and the full late fee on May 30th.

We’re in trouble now. I serve her notice that she’s to vacate the premises at the end of her lease term, June 30. Now, please note that as of the 6th of each month, we are well within our rights to serve her a notice that says she has 5 calendar days to make payment or we’ll file for eviction. We don’t do that. We keep hoping she’ll figure it out and get back on track like she tells us she’s working on.

In mid-June, we’re camping, and she calls Mr. ODA. She says she’s been praying on it, and Jesus wants her to stay in our house instead of finding somewhere else. Mr. ODA tells her that she needs to make payment to us for that to be considered. She says she’s going to look into her finances and she can probably get us some money that Friday (it was Wednesday). On Sunday, Mr. ODA texts her to ask what’s going on and she says she can’t pay anything towards rent because she “just” paid rent and her last pay check needed to go to other bills. Mr. ODA says we’ll give her until the end of July since now she’ll have less time to find a place, but she needs to get out. Again, our attempt to treat someone like a human instead of us protecting our business 100%.

She paid June rent on July 5. She told us it would be on July 3. On the 4th she hadn’t paid. Mr. ODA asked where payment was and she said “it’s coming.” She paid rent and the late fee that Sunday morning after more follow up.

She told us we’d have rent on July 31 before she moved out. On the 31st, she said she needed more time. She handed me cash on August 1st.

The person who owns the house has bills to pay. If I don’t pay my bills, the bank could take the house away. So you not paying your rent affects what I can pay. Now, I’m a good person and am always trying to be reasonable. We’ve set up our business so that we can pay our bills even if someone doesn’t have the money to pay their rent perfectly on time. But paying your rent a full month (or longer) after it’s due, with very little communication, and hardly ever following through on the payment date you gave us is taking advantage of us. There was no appreciation for us being understanding. There were hardly any apologies. We were always the bad guy for following up when payment wasn’t being made (while the payment date was actually the date she established and we never forced anything).

THE MOVE OUT

I sent multiple emails letting her know that if she was not out by July 31 at 5 pm there would be fees incurred. She would claim to understand, but then at 3:20, she told Mr. ODA she wasn’t going to make it. Mr. ODA said to move everything to the garage so we could start working on the house to get it re-rented. Well, there’s no lock on the door between the garage and the house, so that plan didn’t exactly work to get us a secured house while she finished moving out.

I will say that she kept the house in great condition. There were chew marks on molding, which says she may have had a dog that wasn’t authorized, but she had the carpets cleaned by Stanley Steamer and the house was cleaned up when she vacated. It’s always a risk when you’re telling someone to get out because they haven’t paid rent that they’re going to destroy something or leave trash behind.

She kept trying to tell Mr. ODA that she’d be done by 8, then 10, then midnight. She really expected us to meet her to get the keys at midnight. Then around 9:30, she texted Mr. ODA saying she was really just too tired to continue and would need to finish it the next day. I met her out there at 9 am. She said she couldn’t get a u-haul and needed more time, but her truck reservation was for 5:30 pm. I literally said that the goal post keeps moving so how was I to know that she’d actually be out of there that night. She tried to give me the keys to the house at that point, but I had to explain that if she gives me the keys, then it’s on me to drop everything and be available when she got the u-haul, and it wasn’t fair to me to keep having to show up to be told she wasn’t done.

Well, she ended up getting the u-haul a bit earlier and was able to text Mr. ODA that she was ready to turn over the keys. She did eventually get everything out (well, except for two cabinets in the kitchen).

But that wasn’t it. Mr. ODA decided to offer to get her the mail that was in the box. It was really because she wanted to check on the 1st one final time, but Mr. ODA didn’t head out there with the mail key. So after multiple back and forths, they finally decide to meet at a park in town. She then shows up a half hour before the agreed upon time because she was able to get out of work early. Well, that’s not how meet ups work. I just can’t comprehend the number of times that this lady thought that we just sit around waiting for her to decide to need us and that we were just going to magically appear when she rubbed her genie lamp. So Mr. ODA went out of his way to get her the mail, and she was bothered that she had to wait – even though he was 8 minutes earlier than the agreed upon time.

SECURITY DEPOSIT

In the end, it wasn’t bad. She got 80% of her security deposit back. I charged her for a broken stove burner, trash removal from the kitchen, and a stained toilet seat that needed replaced. The house was very clean, so I didn’t need to put much time into that.

SUMMARY

She lived there for less than a year, but she was one of the hardest people to manage. I try really hard to establish a relationship with my tenants that says I’ll treat them with respect and understanding if they treat me with respect. I get praised and thanked up and down from my other tenants. This one wasn’t like that. She thought our bar of understanding needed to be way too high and was completely unreasonable. We were as gracious and patient as we could be.
September Financial Update

RENTAL FINANCES

It’s the calm before the storm with rental payments. We’ll owe multiple jurisdictions’ tax payments over the next month. We only have 5 houses with an escrow account, so I’m responsible for insurance and tax payments on my own. I don’t mind it because that means I don’t have to keep money tied up in an escrow account balance, but it does mean that there are large outlays multiple times a year that need to be properly accounted for.

I recently made a post about late rent payments this month. The one who I continue to charge late fees didn’t even pay on the day they said they would. I despise having to hunt tenants down for payment. She emailed me that “September 5th payment” would be late (ugh … it’s due on the 1st, maybe plan for that day instead), she said it would be paid on the 8th. I had to ask on the morning of the 9th where the payment was. I was giving her a few hours to respond and planned to send a notice of default. Lucky for them, I got distracted and busy, and I didn’t get around to it. They finally responded Saturday night that they had lost power and were distracted, but they sent payment then.

I paid out the invoice from our handyman that I had been waiting on, which was $810. I had mentioned that I’m waiting for an invoice from our HVAC guy, but I think he’s not charging me for the service since he had to go back after installing a new condenser. I’m STILL waiting on the roofer to complete the job on one rental. I signed the proposal on July 5th. He finally started the job at the end of August, but decided to change my scope of work without approval. That delayed the project another week. Then I have no idea what has happened over the past week and a half, but supposedly it’s finally done.

A plumber came out for a hot water heater issue at one of the properties. The tankless water heater wasn’t powered on. I don’t even know how that happens, but it seems like something that may become a bigger issue. The company even said they don’t service or work on electric tankless water heaters, so I don’t even know where we would go from here.

PERSONAL FINANCES

In my last financial update, I mentioned that our insurance adjuster had finally came out, three weeks after the tree falling on our deck. He took a week to get us the estimate. We then responded the next day with all the errors and omissions in the estimate. It then took 3 weeks for our email to be acknowledged (even with multiple phone calls). We finally escalated this two weeks ago (State Farm doesn’t make it easy to escalate beyond your desk adjuster answer the phone), had an estimate redone by our adjuster (supposedly) about 12 days ago, who then told us the supervisor approval process would be 3-4 days. Giving the holiday of Labor Day and benefit of doubt, we didn’t push it until Monday, hoping they’d do the right thing and get us information. Mr. ODA saw that we had been reassigned a field adjuster on their portal. So guess what? For an event that occurred over 10 weeks ago, we’re starting over! Lovely.

I paid the kids’ tuition for preschool late. Luckily there’s no late fee charged. The school “opens” links each month. I tried to pay it around the 20th of August for September because I knew the last two weeks were going to be crazy with visitors. When I couldn’t pay it that day, I completely forgot about it. I was part of the “hey, you didn’t pay” email from the director – so embarrassing. Our oldest is going 5 days a week, so now his tuition is $350 per month; our second’s tuition is $175 per month.

Our 0% introductory interest rate on our credit card we opened 15 months ago expires at the end of this month, so that’s over $5k that needs to be paid. Then our credit card statement balance owed on our regular card is about $4,800 because of large rental property expenses. I haven’t paid it yet because I need to transfer money from savings, so I’m waiting until the last minute to do that so we can earn interest on that amount.

NET WORTH

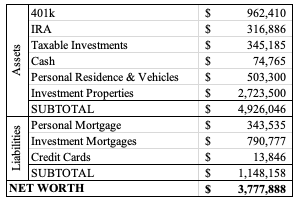
Nothing too exciting to note here. Credit cards are still high, but that will be significantly different next month with our 0% interest card being paid off.

I asked Mr. ODA for his 401k updated amount yesterday, and he made a comment that I should wait to update until today because the market went up yesterday. I had already done the majority of the work, but an ailment and children meant I didn’t get to posting yesterday. So this morning, I updated just our investment account totals to see the difference. The chart above is yesterday’s numbers. Today’s 401k, IRA, and taxable investment account totals are $10,000 higher today than yesterday. That means that if I had updated the numbers today instead of yesterday, we’d be showing an increase in net worth from last month’s update by about $6,000. Instead, I’m showing a slightly lower net worth by about $4,000. It just goes to show how much the market can affect the numbers on any given day, and my net worth in trending generally upwards, but it may not seem that way because of one day’s market closure.

Expense Tracking

In January, I mentioned how I have a very detailed spreadsheet to track my expenses. I started this spreadsheet concept in 2012 when my husband and I started combining living expenses. We also moved from NY to PA to a VA apartment to a VA house in a matter of 22 months. I needed to have a way to make sure I didn’t miss any bills. I didn’t want to rely on receiving the bill itself in the mail or in my email before paying it. I chose to develop the spreadsheet based on our pay check dates, which were every 2 weeks.

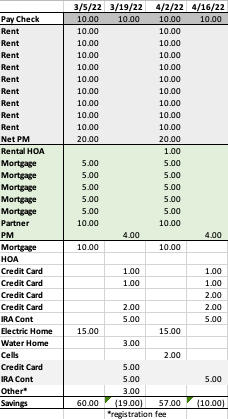
Here’s my sheet, in essence. Pay no attention to the actual numbers in this screenshot, as I didn’t take the time to make sure they were made up but still proportioned to each other. The format is exactly as I use it though. I set it up at the beginning of each year.

For the entire year, I record the pay check receipt across the top of the sheet. The dates are based on the day the money hits our account. This has changed over the years, as we used to get paid on Tuesdays, but now Mr. ODA’s pay check shows up in our account on a Saturday.

The first section, which is all gray, is the rental income. I then record all the rental income near the 1st of the month. If a pay check isn’t near the first of the month, I record it for any pay check date that shows up in the first 10 days of the month. Realistically, I receive the majority of our rent on the 5th of each month, so it doesn’t make sense to record it as a projection any earlier than the 1st, and as near the 5th as I can. The ‘Net PM’ is because I don’t collect rent on our KY houses; the property manager collects rent, removes their expenses, and then we receive the net by the 10th of the following month.

The next section is the light green, which captures routine expenses on the rental properties. I record the HOA due date every 3 months, each month’s mortgage payment, the payout to our partner (I take in all the rent each month and then pay him out his half plus our half of the mortgage payment), and then the VA property manager’s expenses.

The white section covers all our personal expenses.
– The bottom two gray lines are simply an indication to me that those affect Mr. ODA’s account and not our main checking account.
– I pay our personal mortgage near the 1st of the month (some time between the 1st and the 10th, but I typically prioritize this getting paid as close to the 1st as possible).
– Our personal residence’s HOA is only due one per year, which is why there’s nothing on that line for this particular snapshot.
– Then I have all our credit card payments. For the year, I project based on the previous year’s average bill. As I get closer to the statement end period, I update the projection. If I project that a credit card bill is going to be $1000, but as we spend through the month, we had more expenses than I thought, I update the projection on the spreadsheet to reflect that. So where it said $1000, I may put $1700 to cover my savings projection.
– I project our my utilities too. I know that I have an electric and water bill each month, and I have a cell phone bill that I pay in 3-month increments to my sister-in-law for a family plan. When setting up the sheet for the year, I simply keep the same numbers from last year for the utility lines. While I can log into my account and see the details, it’s easier if I already have it laid out like this. Then I can see, “last year, for this month, my bill was only $40; why is it $70 now?” One caveat here is that I usually keep the lines on this sheet to those items that are going in or coming out of our checking accounts. The water bill can now be paid by credit card (since we moved to KY last year). Technically, I should remove that from the sheet because I track bill due dates separately from this part of the sheet, but since I’m used to tracking the water bill’s due date like this, and I like seeing how the bill changes from last year’s amount due, I’ve kept it on the list.
– I have our IRA contributions listed as well, since that’s a big chunk that comes out each month. The maximum contribution into a Roth IRA is $6,000. We have automatic contributions twice per month, so that’s actually $500 out of each ‘pay check’ grouping.
– The “other” line is for expenses that happen every year, but they aren’t worth having individual lines because there’s only one or two payments per year. As I type that, perhaps my own HOA payment could be added to the other line since it’s only paid once per year. In Virginia, we had personal property tax that would be due each year. We also have our taxes that we owe (because we purposely plan our taxes so that we don’t get a refund because that means you’ve given Uncle Sam an interest free loan). We have vehicle registration fees due. All these ‘one off’ payments are recorded on the “other” line and then I describe the expense two lines below with the asterisk.

As for the savings projection, this is probably mislabeled. It has always said ‘savings,’ but it’s really just the net of that two-week period’s income and expenses. To know if I’m in good shape (if perhaps I’m in a position where my account balance is being kept really low), I net the two ‘savings’ next to each other (so I would add the $60 and the -$19 to know that my income from that first two-week period will cover my expenses for the second two-week period also).

In practice, as I receive the income or I pay a bill, I change the text from black to gray. This tells me that it’s paid and accounted for. I also update to actuals as I go. So if I projected a credit card payment to be $150, but the actual payment was $147.34, that’s what gets put in the sheet when I make the payment. This helps me track actual amounts through the year, as well as sets myself up to create projections for the next year.

I have a separate tab in my workbook that tracks additional income for the year. For example, when I was working part time, I recorded that income on that other spreadsheet. Each time we get money from our credit card rewards, it gets recorded on my income spreadsheet. By keeping track of our additional, unplanned, income, I have the ability to identify our actual savings net for the year. I take the ‘savings’ bottom line from this spreadsheet and add all the additional income we’ve brought in from the other sheet.

While I’m not budgeting the details of our expense categories (e.g., $300 per month for groceries), I’m tracking my income and overall expenses based on bill payments. Last year, I had tracked my expenses by category to see if overspend in one area in particular. I didn’t keep up with it though because the billing cycles didn’t line up with when I’d be running my financial update, but I hope to get in a better grove this year. This set up makes me feel comfortable that I’m not missing a bill. If I get to the end of a 2-week period, and I haven’t grayed out an amount, then I know it’s time to investigate why I didn’t receive mail or an email prompting me to pay a bill. Usually what happens is I’m tracking Mr. ODA’s credit card payment and wondering how much longer he’s going to wait to pay it until the due date. 😛

I hope that was easy to follow. I don’t want to put all our exact numbers in there, but I wanted to share how I “budget.” If you have any questions, don’t hesitate to reach out!