September Financial Update

I really thought I’d be more on top of managing our expenses and categorizing them this year, but it just didn’t pan out. Our spending is higher than I would like in the food category, but I just can’t seem to carve out time to manage that. I did put effort into a Kroger run. We shop Kroger and Meijer (main grocery store chains in this area) for their sales, and we usually use this to stock up on pantry type items. Usually Mr. ODA handles the details because he can recall the average prices and the trends of sales, but we were running low on cereal options, so I checked the Kroger ad and made a list while I could sit and compare prices at Walmart. I learned a lesson on how some things are only deals on the weekend, and then another lesson that if you’re shopping the weekly ad sales, don’t expect everything to be in stock at the end of the sale period. But it’s fun to watch your total go from $135 to $77 when you press check out on the self check out screen!

We’re still carrying $13k on a 0% interest credit card until closer to the end of the year. This was a couple of rental issues and our house’s new windows. Whenever we have a big purchase coming up, we open a new credit card to give ourselves a “free” personal loan. It works out to be about every 18 months we have something to put on a credit card. We started this with IVF for our oldest. A few years ago, it was new carpet for the house. This time it was new windows for the house. We have the cash to pay for it, but we also believe in leverage. We also don’t go for any 0% promotional offers when purchasing from another company (e.g., furniture, windows). When we open a credit card, we get some sort of other offer (e.g., cash back), so if we’re going to take a credit hit, we may as well get $200-500 back on it.

We’re about to go down our first braces road. It’s not fully braces, but a gentle expander to help open his airway. It should help get his jaw more in alignment by helping him breathe through his nose at night. As a byproduct, it should help with some crowding he’s experiencing, although the orthodontist wasn’t concerned with his level of crowding at his age. It was an eye opening experience. The mouth told these two guys a ton of information about my kid’s lifestyle and needs.

I’ve backed off a lot of hours with my job. I’m working from home and managing a few things in the background. My motivation has been lacking, but our youngest started school, so I have more time to get things done. The beginning of school has a lot of activities, so I’ve been focused on that mostly as I’m on the PTA board. Two HOAs are active right now, and one HOA barely does anything so I just check those emails and move on. One HOA has a revamp of the deeds and restrictions, and another one has a major insurance hurdle we’re working through.

We allowed one of ours to do two sports this fall. I’m quite against the concept because you need to be committed to a team for the sake of the team, so I don’t like when kids chose between two options and then one team is left with a hole. But the baseball season usually doesn’t touch weekends, likely for the fact that most kids are doing soccer and flag football on the weekends. This year, they had to include a couple of weekends because of field maintenance in October, so we’ve been run ragged around here. The end is in sight next week though. We’ve been doing baseball multiple nights, one night of soccer practice, two nights of gymnastics, and then soccer and baseball games on Saturdays. We’ve even had a Sunday make up for baseball. We haven’t been double booked all that much. We were going to miss soccer practice for a baseball game, but then the league cancelled practice due to heat. Our daughter is going to leave gymnastics tonight a bit early so that we can be at most of the baseball game.

RENTAL PROPERTIES

I’ve been pretty down on the rentals lately. They’ve required a lot more attention, and it’s not easy attention. If it was just calling out a trades person to handle an issue, that’s fine. Instead, I’m managing people and their emotions. That’s not my role. I don’t need to know your life sob story. I don’t need to know all the details about what is happening in your marriage/divorce. Your job is to pay me rent on time, and if it can’t be on time, communicate that. My job is to collect the rent and keep things in working order.

As of the 8th, we had $2300 remaining on rent collection (granted $750 of that is expected because that house is on a twice-per-month lease agreement). One house told me well in advance that they were going to be late because of a new job and the delay with the first pay check. One house strung me along up until the very last minute that part of rent would be late. And another house said that she’d have no problem paying rent even though she broke a toe, and then proceeded to only pay part of rent with zero communication on what’s happening. She eventually said she would pay the rest by the 16th. Managing 14 rentals isn’t easy, but I still recommend having multiple because when people don’t pay their rent, you have enough coming in to cover expenses on the houses.

My previous post outlined the details of a turnover that I was working on. That involved calling out HVAC to fix a frozen line. Outside of managing that and late rent payments, my other time was devoted to a house that we’re going to sell.

Yup. That’s where I’m at. It’s a small 800sf house with 2 bedrooms and the bathroom is only accessible between the two bedrooms. It’s not in a great neighborhood (actually, the area itself is a great location and there’s been a lot of turnover/renovation, but literally across the street from our house is an apartment complex that pulls some pretty bad things). I also have A LOT to say about the tenants that left this house and what we’ll have to do to turn it over, but for now, our energy is going into turning this place into a listing. We’re currently deciding between a 1031 exchange and just keeping the money to put towards a pool. As I’ve said: I’m over the rentals at the moment. So I’m leaning towards eating the capital gains and getting a pool put in. The biggest deciding factor right now is that I’m tired of having to put the stress into finding a fall/winter tenant, so I’m not all that interested in purchasing a house in October/November/December. Perhaps if we list it in a month or so, and it sits for months into the spring market, I may change by mind.

NET WORTH

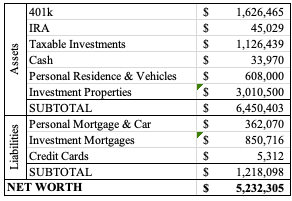
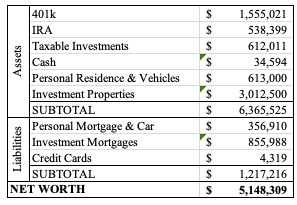
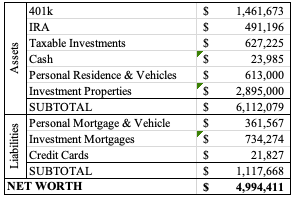
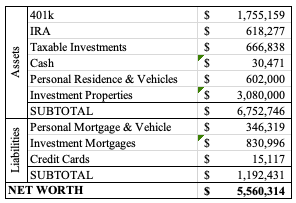
Well, it went down. But I was surprised it was up last month. We haven’t made any move, and we’ve lost about $4,000 of projected income with a vacant house while we get it ready to list. The house is paid off, so all we need to manage at this point is the electricity. Our credit cards are a decent chunk lower; our spending has been low this month.
February Financial Update

Before I get into an update, I have a quick perspective moment. Our preschool has a 3.5% processing fee to pay monthly tuition online. Tuition is $265, so the processing fee comes to $9.27. If I paid it online instead of writing a check each month, that would be an extra $83.43 I paid for basically nothing. For perspective, I spent $82 on a grocery run of essentials (e.g., dog food, paper towels, milk, eggs, etc).

RENTALS

I had to give notice to one household by 1/31 if I were to raise rent. Their lease ends 3/31, and that will mark 3 years with me. I was panicking because it’s our most expensive house (it’s also our nicest and biggest, and it’s fairly close to downtown). Rent has been $1750 for the last 4 years. Last year I missed the notification to raise it because a January deadline surprised me, but this year I put it on my calendar for January 1st to do. And then I dragged that calendar reminder through the whole month, only needing to then set an alarm to make sure I did it at 8pm on the 31st. I raised it to $1800 and they accepted within the hour. Phew. They’ve been late three times in 4 years and clearly communicated what was happening each time. We’ve had two major issues at the house that they rolled up their sleeves and helped mitigate the damage before the tech could get out there. They’re just really great tenants.

I had two tenants pay rent before the 1st and one partially pay before. That was surprising since the last two months I’ve had very late payments come through. I still have one person with a partial payment outstanding as of this morning.

We had a water heater go out on Thursday in one property, but otherwise I’m counting all my blessings that we made it through 2 weeks of below freezing without incident.

PERSONAL

I’ve preached monitoring your spending by writing it down for years, but I hadn’t done it. I had done it a few times retroactively, but I never made the time to keep on top of it to make pivots. With Mr. ODA leaving his career, that’s a high six-figure income that we’re without now. I’m working part time, but that’s basically a one-to-one ratio of income to health insurance. I’ve calculated that we need to be about $1350 per month in spending outside of the mandatory bills (e.g., mortgages, utilities, tuition, insurance). My threshold is lower than what Mr. ODA said is his threshold, so this isn’t a hard-and-fast amount, but one that is my “I feel OK if we’re close to this number” concept.

We screwed that up a good bit by purchasing a new vehicle and putting new tires on said vehicle immediately. We also had to pay for a previous heating issue fix in our house and a downpayment on new windows (which, quick side note, are glaringly needed as we go through 2 weeks of single digits and can feel the drafts). I’m also not counting the things that we do as mystery shops since those are effectively reimbursed (sometimes our cost isn’t fully covered since it’s a whole family outing and not a single person, but I’m not drilling down in that detail since I don’t have the specific break down of how Mr. ODA is getting paid). If I take those things out and remove expenses for rentals, then we spent $1597 in January.

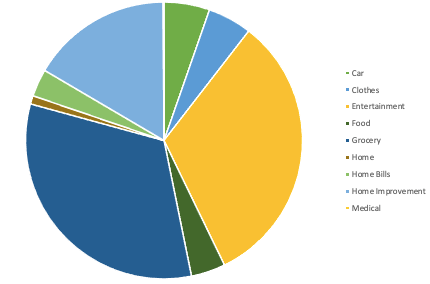
This isn’t the best representation of our spending, but I’ll develop this information as I have comparisons month over month. I also can’t seem to pick a better color scheme without it being a very manual process. Grocery, Entertainment, and Food are our biggest slices there. The entertainment category is basically why I gave up categorizing things years ago. Here I put things like going out for a drink, because while it’s at a restaurant or bar, the sole purpose was to have a drink and hang out. It also includes going to a gymnastics meet with my daughter, my fitbit purchase (I guess because I’m counting it as extra spending and not a necessity), and gift giving costs. We spent $528 on groceries this month, which feels low. I pushed really hard to clear out the food we have in the house already during our 2 weeks of being snowed in, but I hope that this is an accurate representation of monthly spending on groceries.

NET WORTH

It is higher than last month, so that’s good. Credit cards are carrying $4500 worth of windows, so it’s nice how low of a balance those are outside of that 0% interest balance we’re holding onto. Our investments struggled a bit over the past month, but the payments on mortgages and loans helped offset that.

December Financial Update

We are 2 months without Mr. ODA’s pay check. I honestly haven’t noticed because my day to day is just managing how much is coming in against how much is going out. My concern is the net I have for this year is $30k less than what Mr. ODA brought in. We’re adding nearly $2k per month for insurance costs, so that net difference is $42k. That’s a gap we’re going to need to focus on here shortly. I should note that our spending includes rental work that we pay out, and we had some major purchases in there (e.g., roof, HVAC). I could say I hope that our investments in the rentals will be less next year, but we seem to track the same expense totals each year.

End of year means I need to get my spreadsheet organized. I need to make sure all expenses are logged, that all logged expenses have receipts and documentation to support them, and that all our maintenance actions are logged in my maintenance sheet. The maintenance sheet is what I use to check back easily on what work we’ve done on each house. I was taking too much time trying to remember which house we replaced things in, so now I have this sheet that I can pull up and easily say, “I just replaced a valve in that toilet 4 months ago; this isn’t normal wear and tear.”

RENTALS

The 5th was a Friday, so you know what that means – I didn’t see most of our rent until then. After the 5th was over, I was short 25% of our rental income. That is fascinating to me. Everyone had told me what their plan was, but I can’t fabricate money where there isn’t any. I have a tenant that is using a program to pay partial payments throughout the month. I can’t stand it. It ensures I get my money at the “beginning” of the month, while it puts them on a payment plan. However, they have the payment set as the 5th, and then it doesn’t clear and hit my account until about the 12th. I’ve expressed my frustration that this has gone on for several months instead of it being a one or two month stopgap, but nothing is changing.

We got our new townhome rented right before Thanksgiving. That was helpful and a literal last minute prayer that was answered in a crazy fashion. She’s been in for 3 weeks now, and I haven’t heard anything.

I had a tenant inform me that she’s hit rough times and wants to be released from her lease. I was really hopeful for a calmer month, but I need to reset my expectations. 14 rental properties and 12 months out of the year = there probably won’t be a month where nothing comes up. The good news is that we can likely get it turned over and a new person in there for market rent. She’s currently paying $975, and we’re looking for about $1300 going forward. Because she always pays and I knew her financial situation, I’ve always held back on her increases. There was another $25-50 increase coming this year, but it still wouldn’t have made up the increases in carrying costs over the years.

PERSONAL

We’ve just been so busy that we’re not really spending that much. Most of our spending is for regular purchases. We had a huge purchase hit our credit card, but that was split among our family for the purchase of new phones. I did all my Christmas shopping in the last month, so that’s higher than usual spending on the cards, but overall still pretty low.

NET WORTH

I got a new phone number and updated all my accounts before my old number was deactivated (lovely two factor authentication). One of my accounts (401k) updated my phone number, but that apparently didn’t correlate to updated the number associated with two factor authentication – ugh. I need to address that, and for the time being, that’s just a placeholder number that I guessed based on Mr. ODA’s 401k increase over the last month.

October Financial Update

We had two tenants move out at the end of July. We also had back to back trips scheduled for the end of July and beginning of August, with the kids starting school on the 13th. We also had the cruise planned for the end of September into October, so that was a decent push to get the rentals rented before we left. We put countless hours into those two houses and it definitely took its toll.

RENTALS

As of October 1st all our rentals are rented! That’s a good feeling after two months of vacancy. This is the month of taxes. We have several houses that are paid off, which means they aren’t escrowed, and I’m responsible for paying the taxes and insurance on them. The 4 houses we have in KY are owed this month, and it’s about $7k worth. We’ll owe 2 houses in VA that come to about $3k next month.

I have a couple of houses that are struggling to pay rent on time. Usually it happens for a couple of months and they get back on track, but that’s not happening quickly. I’m trying to remain optimistic, but there isn’t a track record of it getting easier if they have taken this long needing to catch up.

We closed on a new property near our house. It’s a townhouse that we hope to get rented later this month. We’ll see what it looks like once it’s empty, but it didn’t appear we’ll need to do anything to it to get it rented (which is how we buy our rentals). There will be separate posts going into the details of each rental turnover and the purchase of House15 using a commercial loan.

PERSONAL

This is the last month for the 0% interest credit card. When we have a major purchase on the horizon (it was house-wide carpet this time last year), we open a 0% interest credit card. We started this concept about 8 years ago. We look for a credit card that has 0% interest for at least 12 months and that gives us a bonus of some sort. We make more than the minimum payment each month and then pay it off before the deadline. A default payment can cause you to lose your 0%, so it’s important you’re making your payments. But we don’t pay a lot towards it because the money is doing more for us in our savings account (or the investments) than it would by paying down a 0% interest balance. This time around was a bit different. The carpet only cost us $10k, but the balance is over $14k. This credit card had the same incentive as our typically used card (2% cash back), so Mr. ODA used it a majority of the time. For a while, my goal was just to pay what gets our balance lower than the original balance from the carpet. But then we had some big rental purchases that we put on the card, and it just wasn’t worth paying $5k+ to the card. We will make a transfer from our big savings account to make that payment at the end of the month.

Mr. ODA’s last pay check arrived on October 11. He took the “deferred resignation program” as of April 30. The sunset date was September 30, so that covered the payout that we just received, including his balance of annual leave.

Outside of rentals, our spending has been minimal. With the cruise, we didn’t spend much since that was a week of almost everything paid for in advance. The dog had his annual check up, so he was the bulk of our costs. We have our routine costs we see, but happy to see lower balances after all the rental work costs.

SUMMARY

I don’t even want to admit what is about to leave our account this month. I guess the positive is that it’s under $100k..? We have to pay the taxes on the houses that aren’t escrowed, pay off that credit card, and buy a house. At least the house purchase goes right towards equity. Since I didn’t get all the account numbers yesterday morning like I planned, here’s an update that captures our new purchase.

August Financial Update

This month was unbelievably painful financially. And yet, I appreciate that we’ve set ourselves up that we can handle these things without stress, even though the balances on credit cards made me feel like I was drowning. At one point, we had over $30k on credit cards. I’m still juggling life as a mom, financial consultant, part time worker, and volunteer on the HOA board. Oh, and managing two vacant rental turnovers, throw in 2 trips away from home, and school starting.

RENTALS

We had one house pay late, with little notice and communication (if you’ve been here, you know this is a pet peeve of mine). They paid the late fee at least. I had another house pay partial on the 3rd and then true up on the 6th. Again, no communication, and she beat me to asking what the deal is. I also had a tenant who already pays twice per month be late on both of this month’s payments, so that also brought in late fees.

In a story for another time, we have two vacant rentals. 11 of 13 houses renewed. Two houses each actually moved out of state, and unfortunately, my kind heart scheduled both of them to end their leases on July 31st. We’ve been spending all our time at these two houses. The one had smokers in it (against the lease) and we’re struggling with that. We’ve replaced the carpet and painted all the walls (except 2 closets and a powder bathroom) and it still smells funky when you walk in. Then there’s just the routine type turnover things like scrubbing and wiping dirty hand marks off the door frames. All of these things will be detailed in separate posts. The other vacant one was quite the story, so that’ll be multiple posts. Our attention isn’t as heavily on that one because we’re going to likely sell it instead of re-rent it.

We replaced a roof ($5500), replaced an HVAC ($8300, but split with a partner), evicted bats ($1480), and made decisions on flooring replacement in another house with extensive termite damage. Seriously. Financially painful. Coming this next month, we will also be paying for termite repairs at another house where we tore out carpet and laid LVP.

HEALTH COSTS

I tend to focus heavily on this topic in this blog. It’s surprising because it’s not really the niche of making money, but insurance and doctor bill processing seem to be wrong more than they’re right. Therefore, it falls more into “protect your money” than anything else.

This is a longer story for another post yet again, but the gist is that the insurance company took 6 months to process a claim. They sent me the bill in June. I called 3 weeks after the bill arrived to find out they had sent my balance to collections because their system flagged it as a January overdue balance…even though this was my first invoice on the matter. Love it.

The end result here is that we needed to add $1600 to the credit card.

PERSONAL

I don’t know that there’s much personal life happening with all those other things we’re managing. We took 2 trips. One didn’t cost us much because the grandparents take care of a lot of the cost, another one cost us more than usual because I put a lot of effort into food that we usually don’t do when we travel there. Overall, the trips were fairly inexpensive financially, but they took a toll on me due to the time commitment and what we had to give up by doing these trips.

Otherwise, we’ve just been wrapping up summer and starting school. We’re about to get back into baseball season with lots of practices.

NET WORTH

The market had a big jump last week and my update of financials occurred Thursday morning. Unfortunately, life put a blog post on the back burner while we were turning over a rental, so I’m only getting around to posting this now. The market is in a fairly similar spot as of yesterday’s close, and I’m thinking we’d even be over $5 million if I were to fully update our financial status right now. We’ll just hope for the best for next month.

In October, we’ll pay off our $15k credit card that we’re carrying, so that will be a big swing in our credit card balance two months from now. We need new windows at our house (the seal keeping in the gas between the panes is going on quite a few windows (or went years ago), and it creates this streaky dirty look to them), but I think I’ll appreciate not carrying this large credit card balance month to month while we utilize the $0 interest for a while.

July Financial Update

RENTAL EXPENSES

We took a trip to Richmond, VA to work on rental properties. It was fairly last minute. I had a schedule of work at each house that I planned. However, I didn’t plan on the heat index being 113 and 112 for the two main days we were there. I was able to get everything on my list done except for staining the new deck at one of the houses. I didn’t want to risk it not applying or curing correctly because it was too hot and in direct sun. Plus, the tenant didn’t even clear it off so I could work on it.

I had multiple houses pay rent late this month. I was surprised. One let us know on the 5th that they had an emergency, so they wouldn’t be able to pay until the 17th. I had someone pay half their rent early in June, but then haven’t received an answer as to why the rest of her balance ($345) hasn’t been paid yet. Another tenant misunderstood her maternity leave pay, so she asked for more time to pay rent. She paid $800 on the 7th. I told her not to worry about it, and just pay when she can, without the late fee; she only has $150 remaining.

I’m currently working through two roof replacements. One of them will be covered by insurance, but then I’ll be paying to have vents added, the chimney torn off and capped, and the soffits repaired on top of what insurance can do. Then the other one we’re paying out of pocket for. It’s original to the house, which was built 24 years ago. There has been storm damage to it over the last year, and it’s just generally time to address the age even though it hasn’t caused any problems yet.

PERSONAL EXPENSES

Our medical insurance company had some glitches in their claim processing through the first half of the year. Now they’ve caught up, meaning I’m paying large sums of medical bills. Mr. ODA took on booking lodging for his guys trip later this month, which meant that the second half of AirBnB payments were applied to the credit card.

Mr. ODA increased each kid’s UTMA from $75 to $100 per month. That means we’re investing $3,300 each month into accounts, on top of maxing Mr. ODA’s TSP contributions and both of our Roth IRA contributions for the year.

Our contractor has ghosted us on our own deck build. We bought some new furniture for the main deck area. Once it’s not 100 degrees outside, we’ll work on doing the waterproofing of the deck ourselves so that we can start living on the patio under the deck and get that hot tub ordered this fall.

NET WORTH

I updated the valuation of the houses this month. I typically only do that 3 or 4 times per year. I try to account for the big increases we see at the beginning of the spring, and then adjust slightly around this time of year once the comparable houses have closed and sold. This update added $140k worth of equity into the equation. All of our liabilities decreased since last month, and all our assets increased since last month. That has equated to an increase of over $200k in our net worth.